Is Your Estate Plan Old Enough to Buy a Drink?

Is your estate plan old enough to buy a drink?

If so, it’s probably overdue for a review. As National Estate Planning Awareness Week comes to a close, now is a great time to look at your current plan!

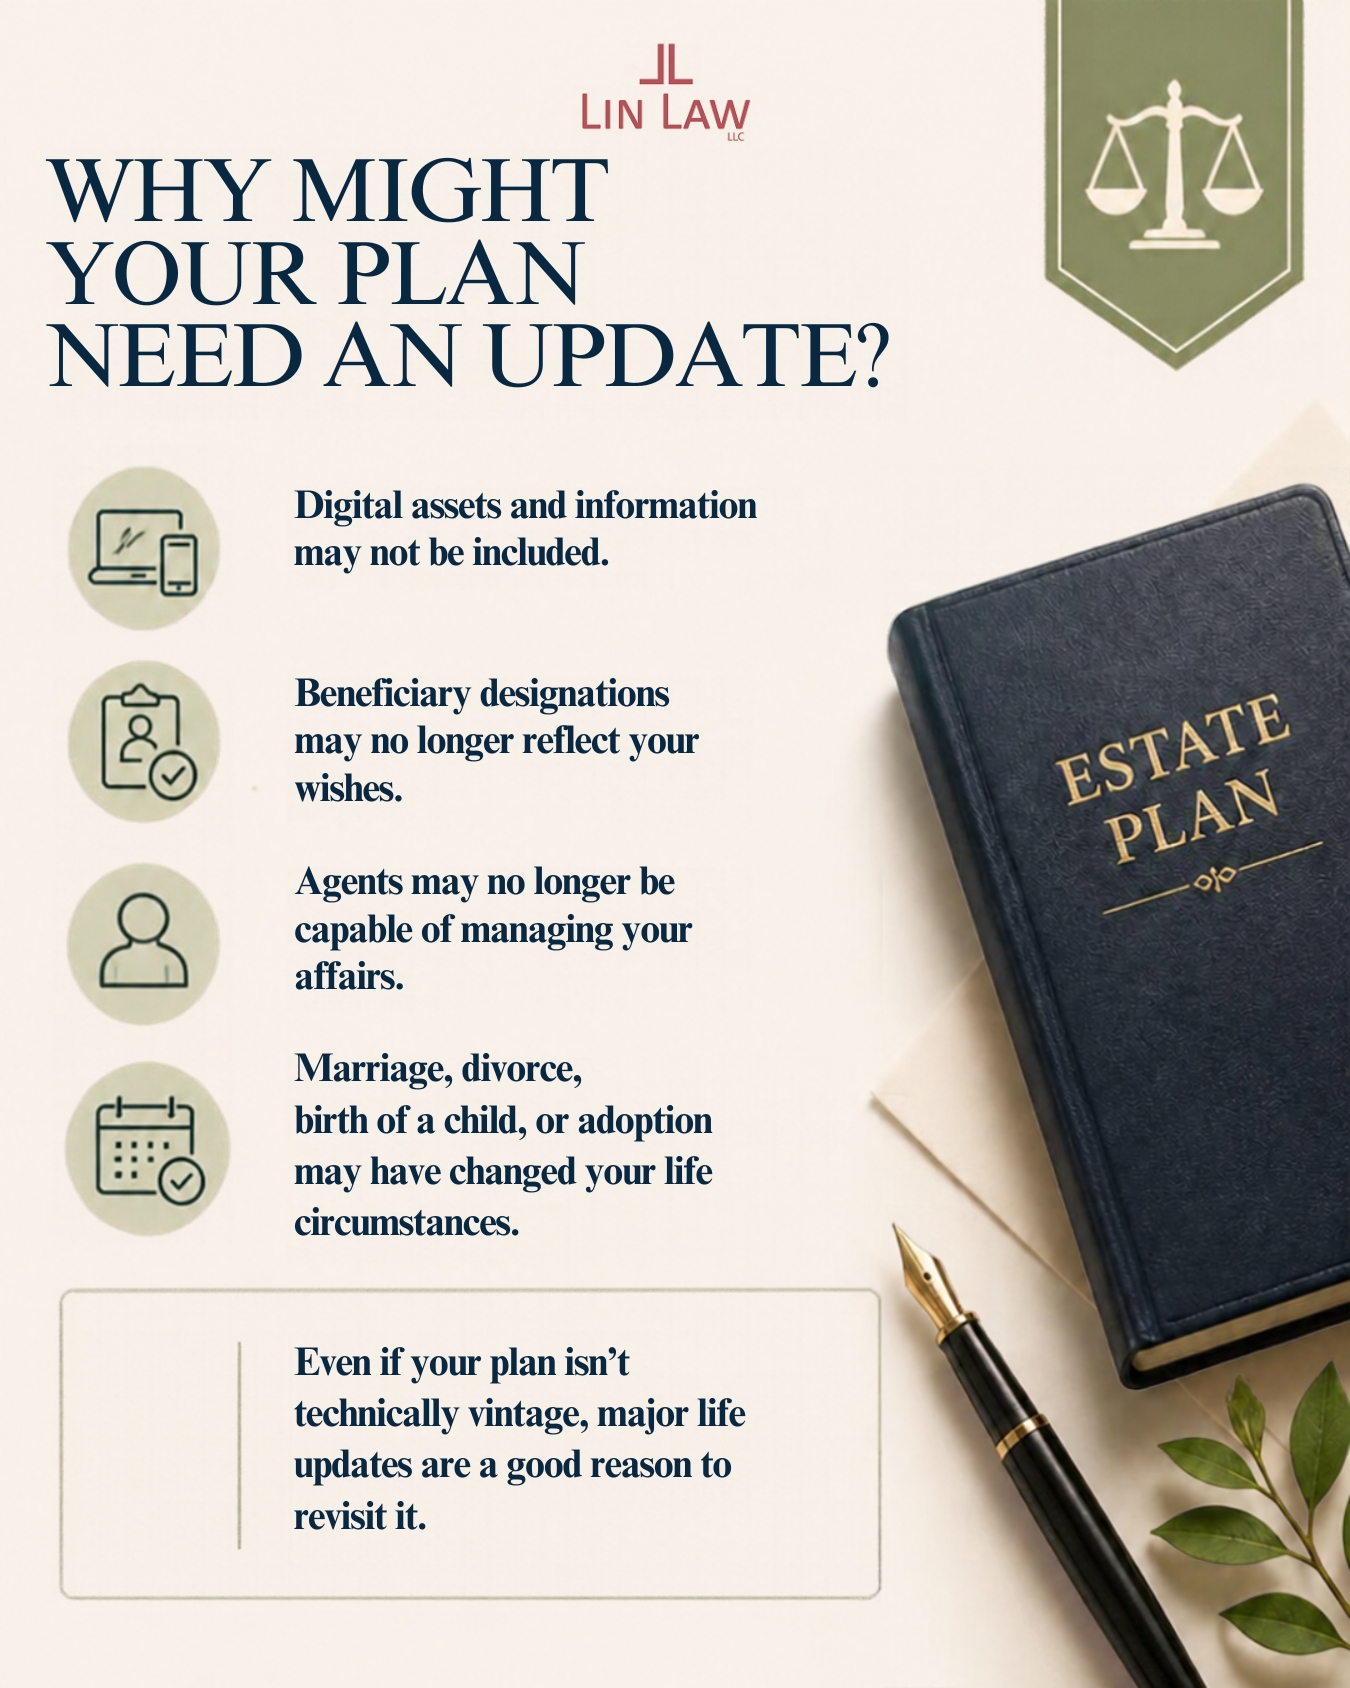
There are several reasons an old estate plan could require an update. Maybe your digital assets and information aren’t included in your plan. Technology has rapidly transformed how we manage our finances and digital assets. Your life circumstances may look very different, too. Maybe your plan has beneficiaries you wouldn’t choose if you were creating an estate plan today, or your agents are no longer capable of assisting with your affairs. Even if your plan isn’t technically vintage, any major personal life updates (such as marriage, divorce, birth of a child, or adoption) also make it a good idea to revisit your current estate plan.

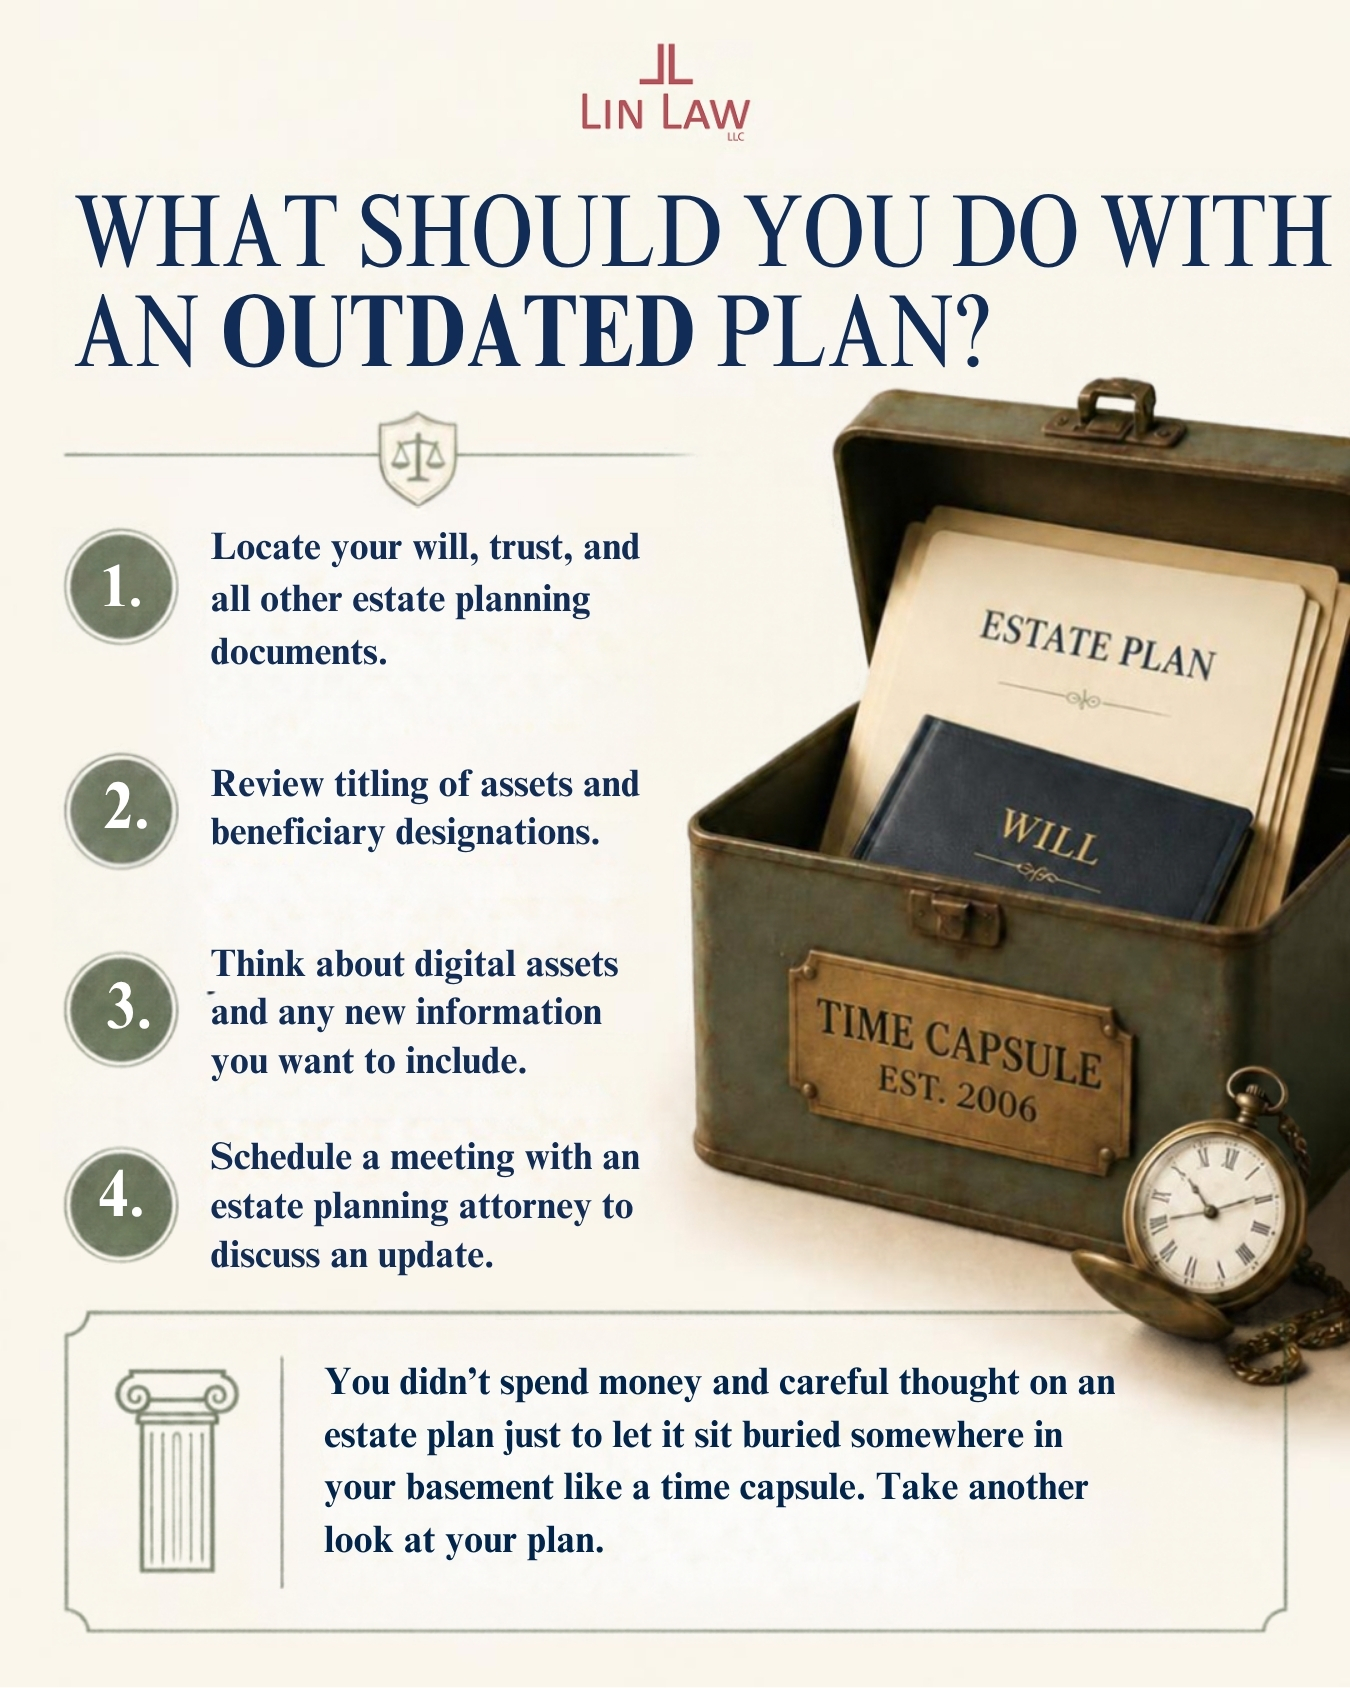
So, what should you do with an outdated estate plan?

  1. Locate and review your will, trust, and all other estate planning documents you have.
  2. Review how your assets are titled, and all beneficiary designations in place.
  3. Think about digital assets and any new information you want to include in your plan.
  4. Schedule a meeting with an estate planning attorney to discuss an update.

Don’t wait for your estate plan to turn the legal age to drive, vote, or drink before you review it. Unlike for your kids, these milestones aren’t just ones to celebrate; instead, they’re signs of a much-needed review.

A properly-drafted estate plan might be timeless in its intentions, but not in its relevance. If your plan was carefully done, you probably don’t need to overhaul it. It may just need a few minor changes to make sure it still reflects your wishes and life circumstances. And if your situation has changed significantly, now may be the time to update your plan.
What Happens to Your Business if Your Marriage Ends?

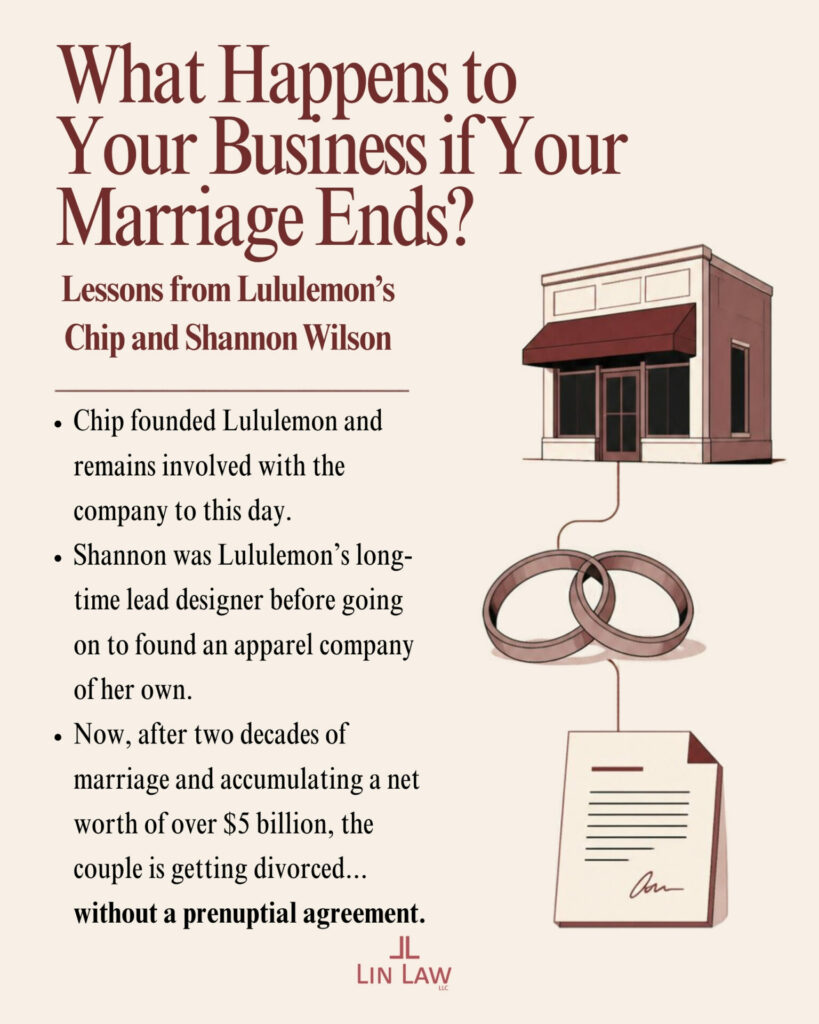
The divorce of Lululemon founder Chip Wilson and his wife Shannon “Summer” Wilson comes with an unfortunate complication. The Wilsons had closely connected personal and professional lives. Both Chip, Lululemon’s founder and CEO until 2005, and Shannon, Lululemon’s lead designer for several years, were directly involved in the company’s operations. Now, after two decades, the couple is getting divorced… without a prenuptial agreement.

This story is a good reminder to consider: what happens to your business if your marriage ends?

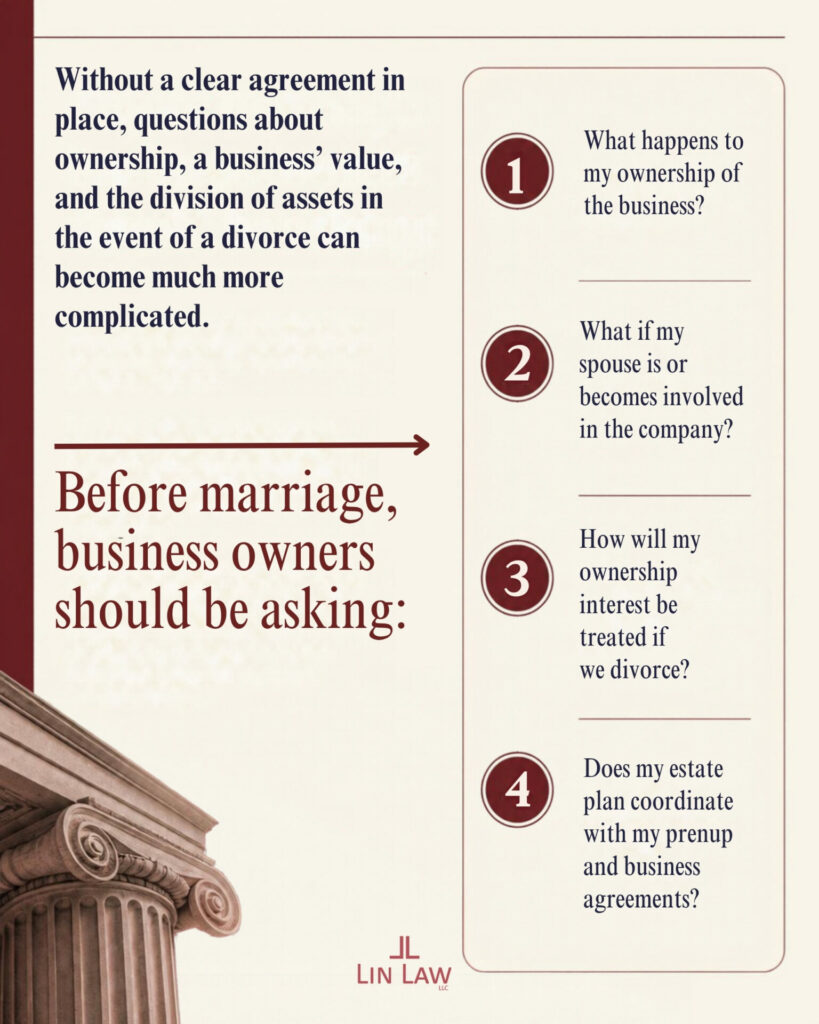
For entrepreneurs and business owners, marriage can have significant implications for business ownership, wealth transfer, and estate planning. The same is true in the event of a divorce. Without a clear agreement in place, questions about ownership, a business’ value, a spouse’s contributions to the business, and the division of assets can become much more complicated.

Before marriage, business owners should be asking:

  1. What happens to my ownership of the business?
  2. What if my spouse is or becomes involved in the company?
  3. How will my ownership interest be treated if we divorce?
  4. Are my estate and business succession plans coordinated with my prenup and business agreements?

These concerns apply whether your business is worth $5 million or $50,000.  Economic value is one thing, but what about ownership, management, control, and liquidity?

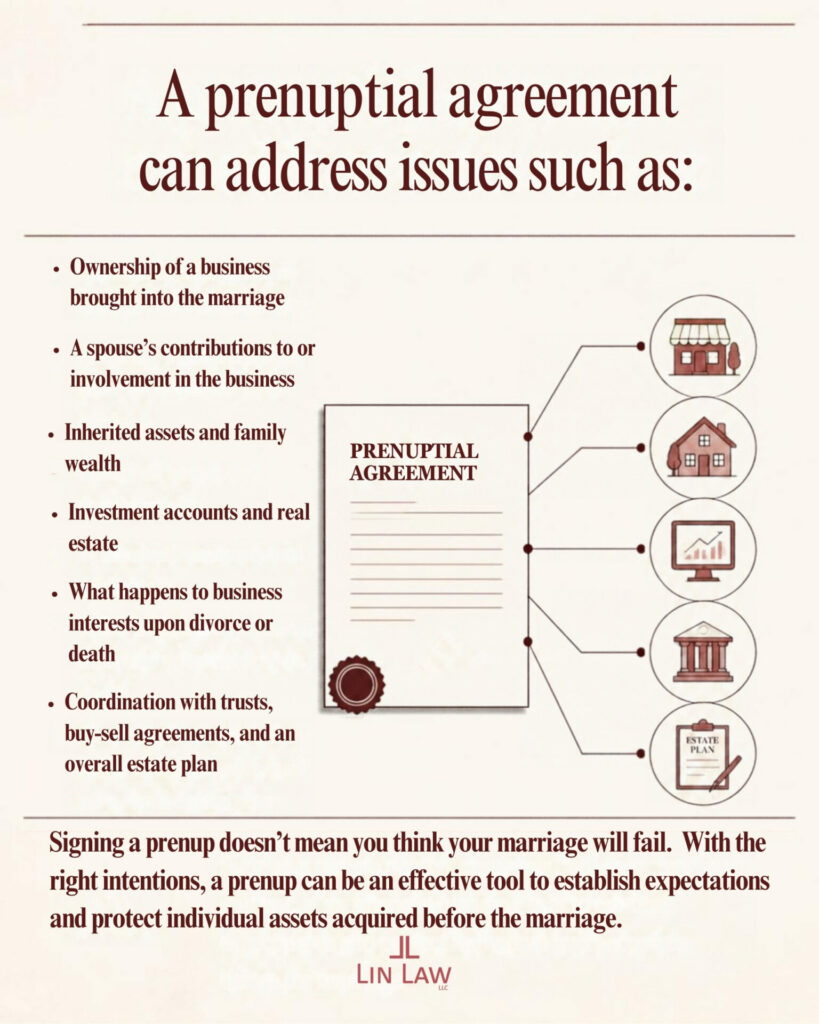
A prenuptial agreement can address issues such as:

  • Ownership of a business brought into the marriage
  • A spouse’s contributions to or involvement in the business
  • Inherited assets and family wealth
  • Investment accounts and real estate
  • What happens to business interests upon divorce or death
  • Coordination with trusts, buy-sell agreements, and an overall estate plan

Signing a prenup doesn’t necessarily mean you think your marriage will fail. If both spouses share positive intentions, a prenup can be an effective tool to establish expectations and treat both parties fairly.

SuperLawyers & Rising Stars 2026 – Evan Y. Lin & Andrew E. Martzahl

Congratulations to our attorneys on their 2026 SuperLawyers® recognitions!

We are proud to celebrate Evan Y. Lin on being selected to Wisconsin SuperLawyers® for his 12th consecutive year, and Andrew E. Martzahl on being recognized as a Wisconsin Rising Star® for the first time.

These honors reflect their dedication, professionalism, and commitment to serving their clients and our surrounding community.

Estate Planning for the Family Cabin


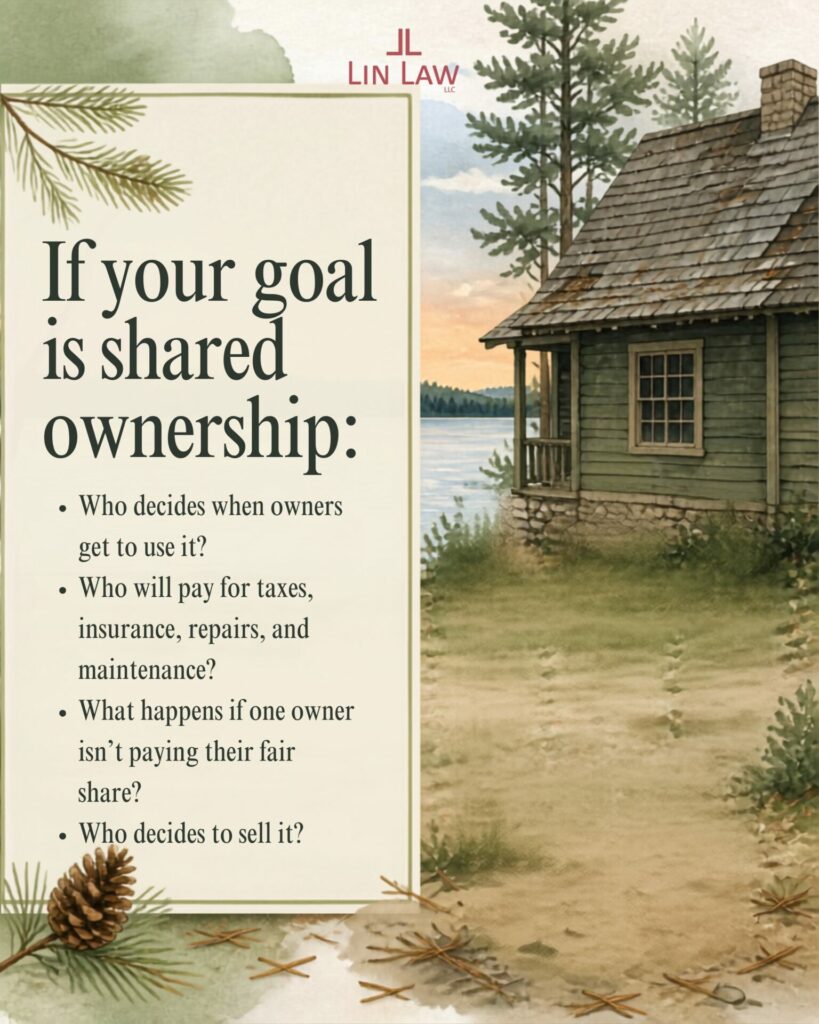
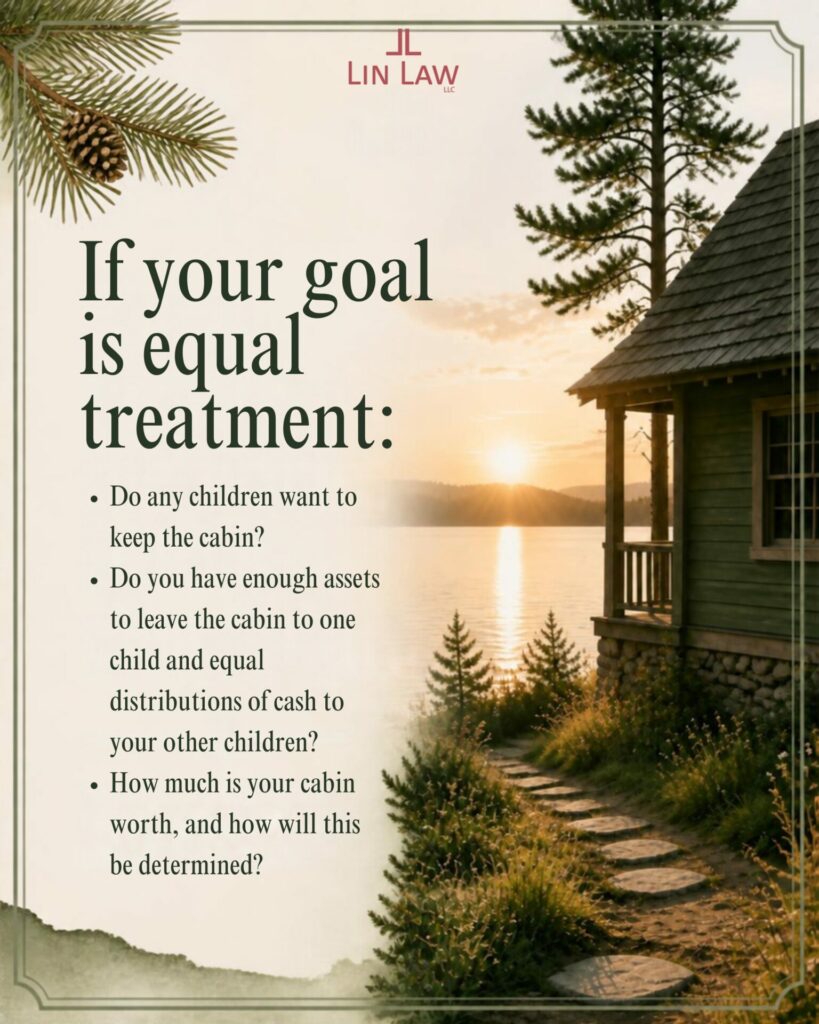
For so many Wisconsin families, summers up north are a source of fun, family bonding, and priceless memories. It’s only natural to want these same memories for future generations of your family. The family cabin, cottage, or whatever name it goes by, are where these memories are made. As the summer ends and you prepare the family cabin for the coming winter, have you prepared it for the long-term future too?

Ask yourself:

1)  What is your goal? Is it to retain ownership of the cabin in your family, to assist your children in buying their own cabin, or something else?

2)  Have you talked with your family about your wishes? What do they want?

3)  Does your plan accomplish your goal?

4) Does your plan anticipate potential disputes and proactively address them?

Without a plan, family cabins are often sold, especially if children can’t agree or if equity in the cabin is needed to provide equal distributions to children. Another common result in the absence of a plan is outright co-ownership among siblings. This presents an entirely different set of problems. Disagreements commonly arise over responsibility for financial upkeep, chores, shared use, and when and for how much to sell the cabin for.

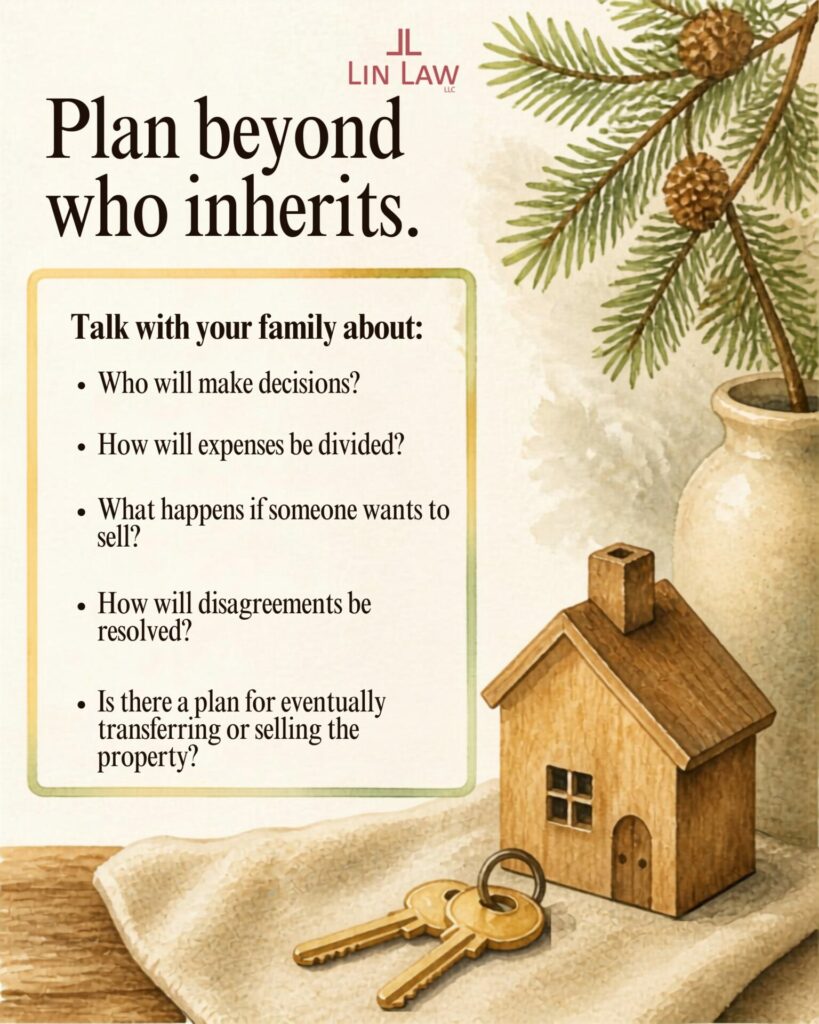
These situations, although common, can be proactively addressed by creating a plan that accomplishes your goals, minimizes potential areas of disagreements, and takes into account your financial situation and your family’s wishes. A thoughtful plan should consider:

  • Who will ultimately make decisions about the property?
  • How will expenses be divided?
  • What happens if someone wants to sell?
  • How will disagreements be resolved?
  • Is there a plan for eventually transferring or selling the property?

Whatever your goals and financial situation, having a plan in place helps ensure the family cabin is a continued source of family unity and joy, not one of headaches and hard feelings. Before you lock up for the season, take a moment to plan beyond next summer and give your family the gift of preparedness.

The Risks of DIY Estate Plans

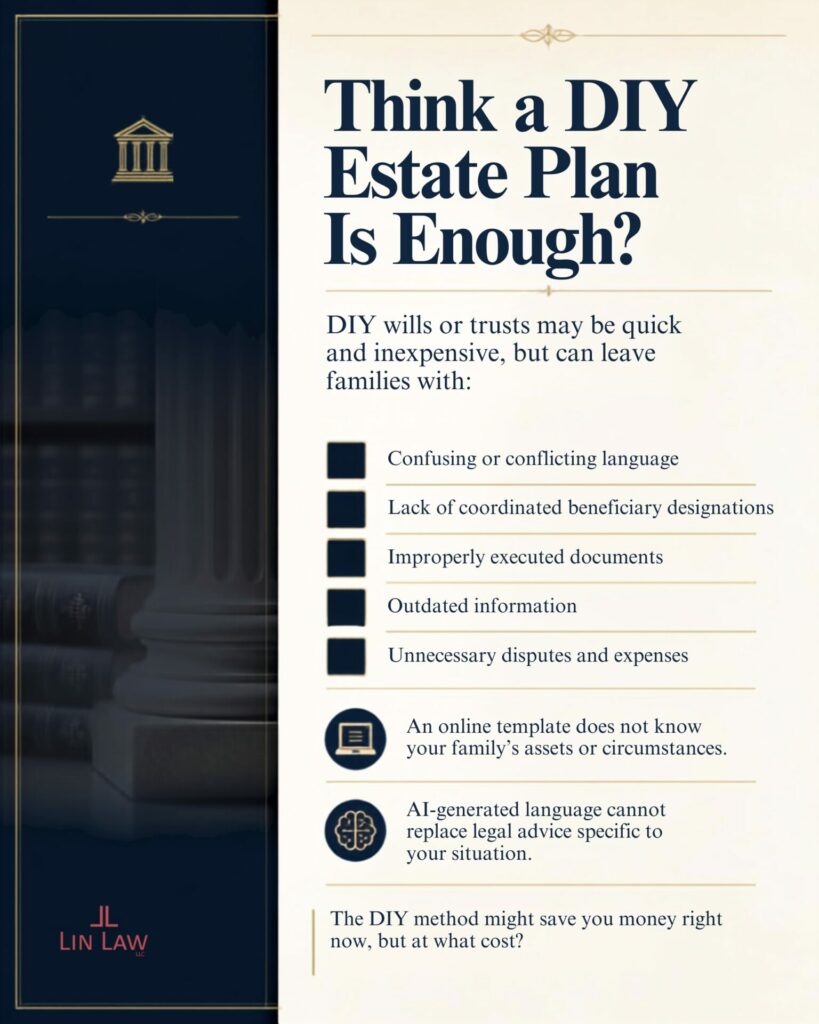
Think a DIY estate plan is enough?

You found a template online. Maybe you used AI to create your documents or perform research. It was quick, inexpensive, and seemed easy enough. But will a DIY estate plan work the way you want when your family needs it most?

An estate plan, regardless of how it’s created, should be: (1) in the proper form; (2) goal-oriented; and (3) contain substance consistent with your goals.

In order to be valid, estate planning documents must be in the proper form.  They must be properly prepared, executed, and consistent with your other estate planning documents. They should also clearly and consistently communicate your wishes.

Form and validity aside, a properly drafted estate plan must have your goals in mind. Unless you tell it, an online template doesn’t know your family, your assets, or your life circumstances. And it doesn’t always ask. Even when it does ask, some things just can’t be fully explained by auto-filling a template or questionnaire.

Some pitfalls with DIY estate plans can include:

  • Placing too many or too few restrictions on access to and management of property;
  • Failing to recognize and minimize areas of potential future conflict; and
  • Missed opportunities for tax or administrative savings.

These may result in unforeseen consequences, leaving your family dealing with problems you never intended.

A DIY estate plan could work just fine, and certainly might be less expensive than professional guidance. But it could also create unanticipated problems. If not done correctly, those savings now might end up costing your family much more down the road… financially or, worse, at the expense of relationships.

If you are relying on a DIY estate plan, it might be time to take another look.

A Lesson from the Los Angeles Lakers Drama

What happens when an inheritance becomes the source of a family feud?

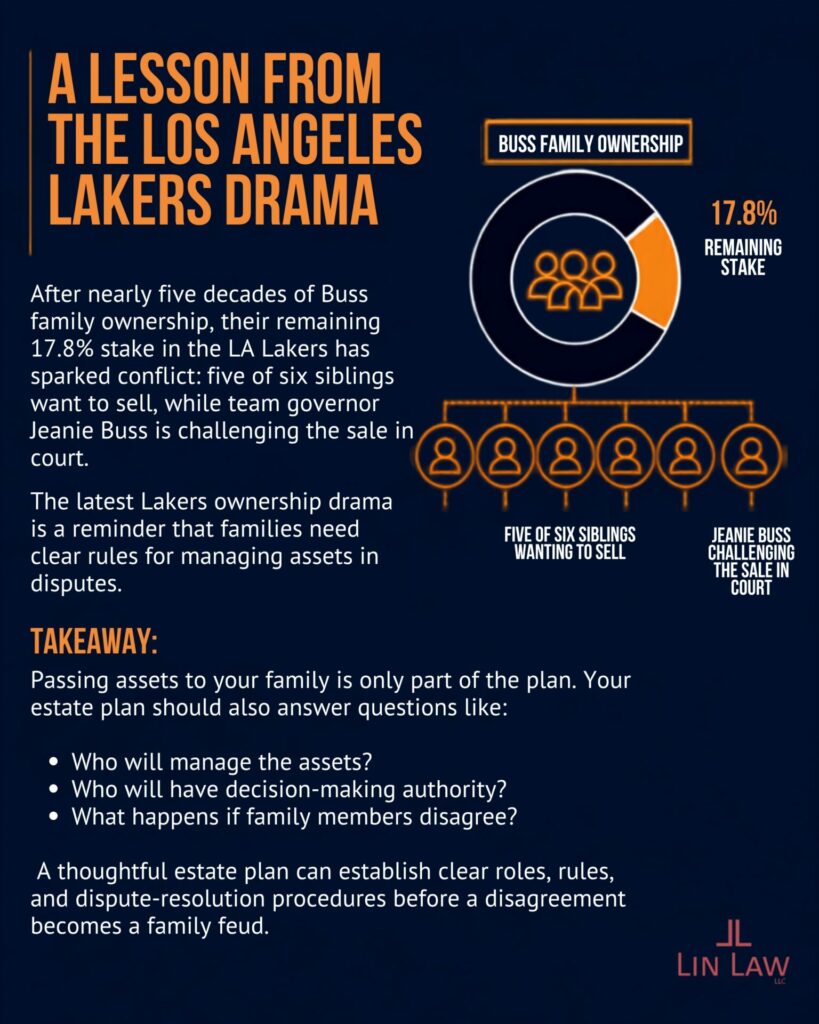
The latest Los Angeles Lakers drama is about more than basketball. After nearly five decades of Buss family ownership, the family’s remaining 17.8% stake has become the center of a legal dispute.

Jerry Buss structured his estate so that his six children would share in ownership of the Lakers and continue the family involvement in the franchise. His controlling ownership was placed in a trust for the benefit of his children. Now, with the majority of the family’s stake already sold, five Buss siblings want to sell the remaining interest. Team governor Jeanie Buss has challenged the proposed sale, and the dispute has moved to court. The legal effect of the trust and prior court orders is now being contested in court.

The recent Buss family drama over control of the Lakers is a reminder that succession planning isn’t just for sports franchises or billionaires. You might not have billions in assets to pass down, but you might have a family business to continue. Passing assets to your family is only part of the plan. Your estate plan should also answer questions like:

  • Who will manage the assets?
  • Who will have decision-making authority?
  • What happens if family members disagree?

Even close-knit families can disagree when significant money or property is involved, especially when it is about who will take responsibility for the family business or the cabin up north.

Hoping that everyone will “work it out” is not the best strategy. A thoughtful estate plan can establish clear roles, rules, and dispute-resolution procedures before a disagreement becomes a family feud.

The takeaway?  You could draft a highly detailed estate plan, but if you don’t prepare for family disagreements, your estate administration may not go according to plan. Discuss your wishes regarding authority and expectations with your family during your lifetime. These important and sometimes difficult conversations could save your loved ones trouble in the future.

Specific Bequests: A Game Plan for Your Packers Season Tickets


If you’re lucky enough to be a season ticket holder for our local sports franchise, you might own one of the most coveted assets in Wisconsin. With more than 155,000 people on the Packers’ season-ticket waiting list (and decades of waiting to get those seats), your tickets may be priceless to your family.
You might assume that your season tickets will automatically pass to your family through your estate plan. However, it isn’t that simple. These tickets are subject to the Packers’ transfer rules. The Packers, like most sports franchises, have specific rules for what happens to season tickets when a ticket holder dies. Tickets may only be left to a spouse or close blood relative, and cannot be transferred to friends. And even when planning to leave your tickets to your surviving spouse or children, certain circumstances must be met.

Season tickets are a license to your seats, not an ownership interest in them. Disputes among family members over who gets season tickets following a loved one’s death often lead to revocation of the tickets altogether.

Avoid this unfortunate result by specifically designating who will receive the tickets. You could also, out of fairness:

  • Establish a plan to share the tickets among your children; or
  • Make additional distributions to children not receiving the tickets.

Your estate plan should also account for the Packers’ ticket-transfer requirements. A provision in your plan can’t override the Packers’ rules, so understanding both is essential. The best way to avoid disputes is to clearly and effectively communicate and have a plan in place ahead of time. If your season tickets are important to your family, account for them in your estate plan.

What Happens to Your Digital Accounts When You Die?

When you think about your estate, what comes to mind? There’s a good chance your home, bank accounts, investments, jewelry, vehicles, and other personal property came to mind. But what about your digital footprint?

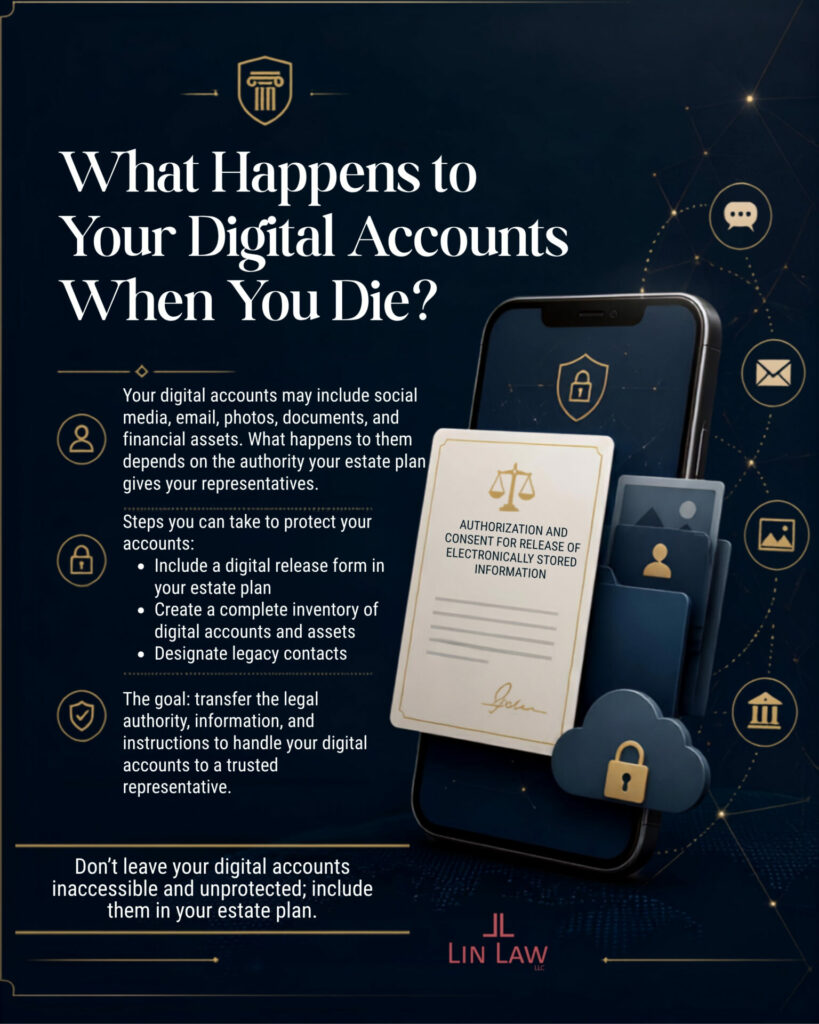
Your digital life may include social media accounts, email, photos and documents, and financial assets. In an increasingly digitalized world, having accounts and sensitive documents with digital-only access is common. What happens to those accounts after you die depends on the type of account, the provider’s policies, and the legal authority your estate plan gives to your representative. Digital assets and accounts require special consideration in your estate plan. Often these accounts are not actually owned by the user. Instead, the ability to use and access these accounts is licensed, and the ability to obtain data stored on them is subject to a user agreement.

An estate plan can include an Authorization and Consent for Release of Electronically Stored Information, a document which gives your representative legal authority to obtain certain electronic records during estate administration. This document can be especially important when family members need information but are not listed as legacy contacts.

Some other steps to protect online assets and information include creating a complete inventory of online accounts, and designating legacy contacts where available.

Planning for your digital accounts also gives you the opportunity to decide which accounts and information you want (and don’t want) others to access.

The goal is to transfer the legal authority, information, and instructions for your digital accounts to your representatives. A proper plan will avoid leaving your accounts unprotected and inaccessible to those responsible for settling your estate.

Your digital accounts are also part of your legacy. Don’t risk losing important files, photos, and memories; include them in your estate plan.

The Truth About Probate, Wills, and Trusts

Probate avoidance is one of the top reasons our clients cite when creating an estate plan. But what is probate? Why do people talk about it like it’s the plague? And if it’s so bad, how can it be avoided?

When someone dies, so does the only person with authority to control their assets. That’s where probate comes in. Probate is nothing more than court-supervised collection of a deceased person’s assets, paying off their taxes, debts, and liabilities, and distributing whatever’s left to the appropriate persons. Doesn’t sound so evil to me.

While probate might not be inherently bad, it takes several months at a minimum. There’s a mandatory waiting period at the outset. This allows persons time to object to the Will and who the personal representative will be. During this time, all assets are frozen. After that, there’s another mandatory waiting period to allow creditors time to file claims. And depending on the size and complexity of the estate, probate can take even longer.

Also, probate (like any other court case) is a public process. All documents filed in probate, including Wills and the inventory of assets, are accessible by anyone. Including creditors, disinherited relatives, curious neighbors, and scammers.

A common misconception is that a Will allows your family to avoid probate when you die. But having a Will doesn’t bypass the probate process, it’s the roadmap for it. A Will designates who’s in charge, and dictates how, in what manner, and to whom assets are distributed.

If avoiding probate is a goal, a properly funded revocable living trust is the most effective and comprehensive solution. Unlike a person, a trust can’t die; it simply distributes assets to new beneficiaries after its initial one dies. Unlike in probate there’s no initial waiting period, so assets can almost immediately be accessed to pay bills and support dependents. And because trust administration occurs outside the courtroom, financial and estate details remain private.

If privacy, efficiency, and probate avoidance are your goals, consider creating a revocable living trust personalized to your priorities, assets, and family circumstances.

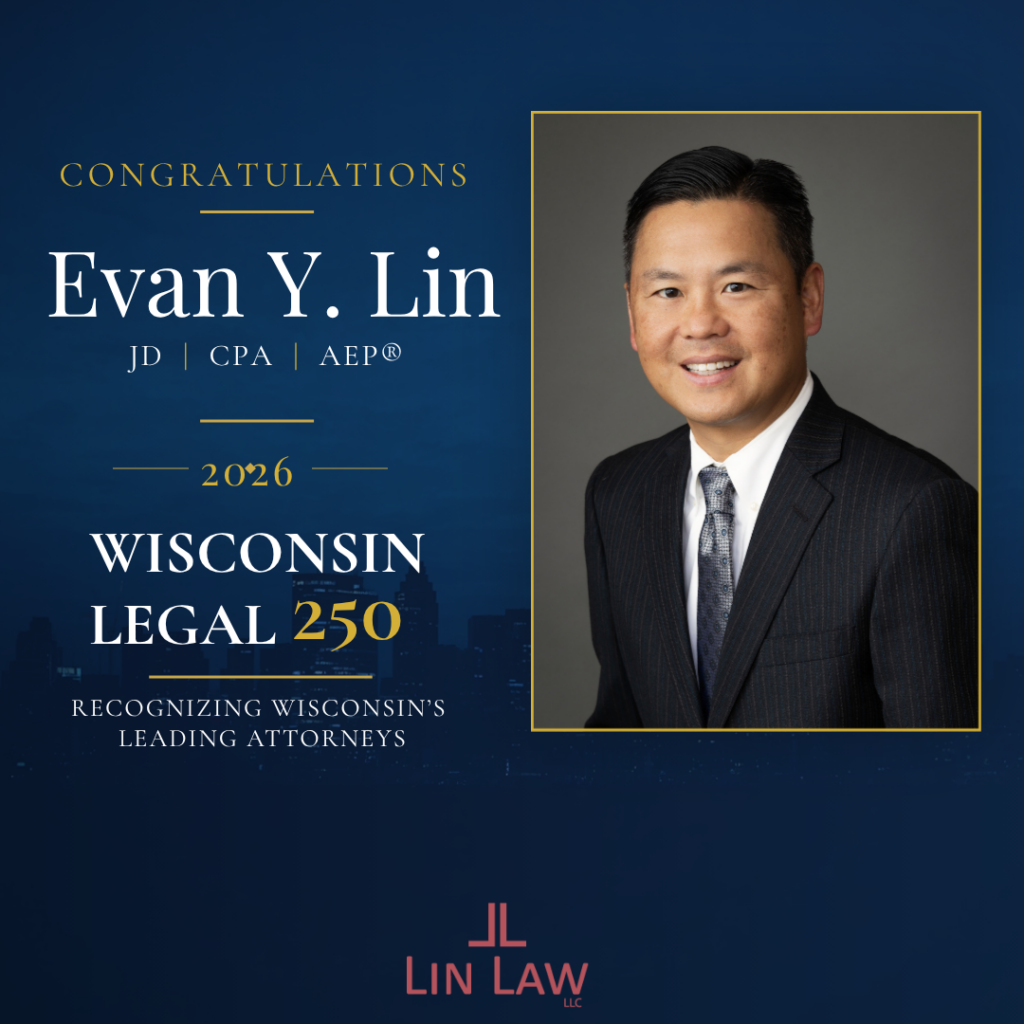
Wisconsin Legal 250 2026 – Evan Y. Lin

Law LLC is proud to announce that our founding attorney and managing member, Evan Y. Lin, has been selected to the inaugural Wisconsin Legal 250 in Business Law by the Wisconsin Law Journal.

The Wisconsin Legal 250 is the Wisconsin Law Journal’s premier recognition program honoring attorneys whose professional accomplishments have distinguished them within Wisconsin’s legal community.  Honorees are selected by the Wisconsin Law Journal’s editorial team based on sustained professional achievement, the ability to adapt to the changing demands of clients and the legal profession, and a meaningful commitment to the communities they serve.

For nearly 30 years, Evan has built a practice centered on guiding clients through business and estate planning decisions with clarity, foresight, and practical judgment. This recognition reflects the impact of his work within Wisconsin’s legal community, and we are honored to celebrate this achievement.

Use this link to view the Wisconsin Law Journal’s Wisconsin Legal 250 https://wislawjournal.com/wisconsin-legal-250/